

The short answer (updated November 2026):
- Mortgage brokers win loans with video that buyers and real estate agents have watched before a deal starts. In NAR's 2026 Profile, 90% of buyers used a real estate agent or broker, so be the lender behind the name an agent gives.
- Run four video series: a rate video every Thursday after Freddie Mac's survey, first-time buyer myths, videos agents forward to their buyers and a refinance watch for past clients.
- Turn the rate into a dated payment change. Freddie Mac's 30-year average was 7.18% on November 5, 2026, down from 7.24%: about $15 a month less in principal and interest on a $360,000 loan.
- First-time buyers are older and put less down than the myths say: a median age of 40 and a median down payment of 9% in NAR's 2026 Profile.
- The rate video takes an hour each Thursday, and the other three series come from one recording session a month.
You buy agents lunch, refresh the rate sheet and answer texts at night. The next loan still goes to whichever lender the agent texted first.
Good marketing for mortgage brokers is four short video series that buyers and agents see every week, so you're the lender they already know when a deal starts. You get a Thursday rate video template filled in with the November 5 Freddie Mac numbers, first-time buyer hooks, a note agents can forward, a refinance text for past clients and a month planned out.
Most buyers meet an agent before a lender, so be the name they look up
Social media brings a loan officer loans when two groups already know your face: buyers in the places you lend, and the agents who tell those buyers which lender to call. In the National Association of REALTORS' 2026 Profile of Home Buyers and Sellers, 90% of buyers used a real estate agent or broker. For most buyers, an agent is in the picture before any lender is.
Loan officers still argue about this. In a June 2026 r/loanoriginators thread, one reply said, "Social media is for realtors." Another answered, "I met all my realtors off social media." The top-voted reply asked the better question: "Is your goal to go viral or to get loans from social media? Thats two different kinds of content."
Make the second kind. I call it qualified attention: the right viewers beat more viewers. A few hundred buyers in your state and the 30 agents you'd love to work with are the whole audience. A viral skit about mortgage jargon reaches neither. Before you film anything, decide who it's for and what they should send you after.
Rates, first-time buyers, agents and refinances: four series, four asks
Four series cover the whole job. Each reaches a different person and ends with a different one-word message, so you can tell which series brings in loans.
| Series | Who it's for | When you film it | The ask at the end |
|---|---|---|---|
| The Thursday rate video | Buyers shopping now, and agents with buyers in contract | Every Thursday, after Freddie Mac's noon release | "Message me RATE for your price range." |
| First-time buyer myths | Renters who want to buy within a year or two | Once a month, in one session | "Message me FIRST for my pre-approval checklist." |
| Videos agents forward | An agent's buyers, through the agent | Once a month, in the same session | "Send this to the buyer who asked." |
| The refinance watch | Past clients and recent buyers who locked high | Once a month, and again the week rates drop | "Message me WATCH and I'll run your numbers." |
Together they cover discovery, depth and decision, the three stages of the content funnel I use for every expert. The rate video and the myths find people. A long first-time buyer guide builds trust. The pre-approval and refinance videos help someone decide to call.
Lead with YouTube and Facebook. The median first-time buyer in NAR's 2026 Profile was 40, and in Pew Research Center's 2026 survey, 91% of adults aged 30 to 49 used YouTube and 78% used Facebook. Add Instagram and TikTok for renters under 30: 79% of that age group used Instagram and 65% used TikTok. LinkedIn is our pick for the versions aimed at agents. One recording feeds them all.
Film a rate video every Thursday, after Freddie Mac's survey comes out
Your weekly anchor is a one-minute video on what this week's rate move means for a real purchase. Film it Thursday afternoon. Freddie Mac posts its Primary Mortgage Market Survey every Thursday at noon ET, an average of rates offered from the prior Thursday through Wednesday. When a holiday lands on a Thursday, it posts on Wednesday instead.
So the topic arrives on schedule. "You didn't have to sit there trying to invent a new topic out of thin air. You just found a conversation that was already happening and joined it," as I say in my video on reaction content. Most rate posts stop at the number. Yours turns it into a payment, then adds your judgment.
THE THURSDAY RATE VIDEO (about 60 seconds)
Film after noon ET, once Freddie Mac posts.
Drop in that week's numbers every time.

HOOK     Rates [rose / fell] this week. Here's
         what it means on a $[price] house.
NUMBER   Freddie Mac's survey: the 30-year
         average was [rate]% on [date], from
         [last week]% the week before. That's
         a national average, not a quote.
MEANING  On a $[loan amount] loan, that's about
         $[change] a month in principal and
         interest. Since [a date people
         remember], it's about $[change].
MY READ  If you're [shopping / under contract /
         waiting]: [one sentence of judgment].
ASK      Want this on your price range?
         Message me "RATE."
ON SCREEN AND IN THE CAPTION
         Example: $[price] price, [down]% down,
         $[loan amount] loan, [term]-year fixed,
         [number] monthly payments of $[payment]
         at [rate]%, [APR]% APR. Taxes and
         insurance not included.
         [Name], [company], NMLS ID #[number]
Here it is filled in with the November 5, 2026 survey, for a $400,000 house with 10% down. Next Thursday, drop in that week's numbers and a fresh read.
HOOK     Rates dipped again this week. Here's
         what it means on a $400,000 house.
NUMBER   Freddie Mac's survey: the 30-year
         average was 7.18% on November 5, from
         7.24% the week before. That's a
         national average, not a quote.
MEANING  With 10% down, that's a $360,000 loan.
         This week's dip is about $15 a month
         in principal and interest. Since the
         February 26 low of 5.98%, it's still
         about $285 a month more.
MY READ  Under contract? A $15 week changes
         nothing. Still shopping? The $285
         since February might change your
         price range, so let's recheck it
         before you tour.
ASK      Want this on your price range?
         Message me "RATE."
ON SCREEN AND IN THE CAPTION
         Example: $400,000 price, 10% down,
         $360,000 loan, 30-year fixed, 360
         monthly payments of $2,438.77 at
         7.18%, [APR with your fees]% APR.
         Taxes and insurance not included.
         [Name], [company], NMLS ID #[number]
The math is principal and interest on a 30-year fixed $360,000 loan: about $2,453 a month at October 29's 7.24%, $2,439 at November 5's 7.18% and $2,154 at February 26's 5.98%, the 2026 low in Freddie Mac's weekly history. Buyers forget a $15 week. They remember $285.
Two rules shape that last block. States set their own rules for showing an NMLS ID in ads, so check yours (here's Virginia's). Under Regulation Z, an ad that states a rate must give the annual percentage rate, and one that states a payment, a down payment or a loan term must also give the down payment, the repayment terms and the APR. So get the template approved by compliance once. After that, only the dated numbers change.
In CreateSocial, the template sits on the teleprompter near your lens, and each block records as its own section. Fumble the math line and you redo that line, not the whole minute.
Answer first-time buyers' myths with sourced numbers
First-time buyers are older and put less down than most of them assume. In NAR's 2026 Profile, their median age was 40 and their median down payment was 9%. Every myth they carry is a video.
| What buyers believe | What the source says | The hook to film | Source |
|---|---|---|---|
| "I need 20% down." | The median first-time buyer put down 9%. | "Most first-time buyers didn't put 20% down. Here's what they did." | NAR 2026 Profile |
| "Pre-approved means the loan is a sure thing." | Lenders use "prequalification" and "preapproval" differently, and neither letter is a guaranteed loan offer. | "Pre-qualified or pre-approved? Lenders don't even use the words the same way. Ask this instead." | CFPB |
| "Help from my parents won't count." | 25% of first-time buyers used a gift or loan from family or friends, and 10% used an inheritance. | "One in four first-time buyers got help from family or friends. Here's what to have ready." | NAR 2026 Profile |
| "I'll wait until rates drop." | The 30-year average ran from 5.98% on February 26 to 7.40% on October 8 and 15, 2026. | "Rates swung about 1.4 points this year. Here's what you can control while you wait." | Freddie Mac PMMS |
Checked against each source on November 9, 2026.
Here's the pre-approval myth as a full script. Buyers need it right before they choose a lender.
PRE-QUALIFIED OR PRE-APPROVED? (about 60 seconds)
For renters planning to buy within a year.

HOOK   Pre-qualified or pre-approved?
       Lenders don't even use those words
       the same way. Here's the better
       question to ask.
ONE    Did they check your income, savings
       and credit? Or did they take your
       word for it?
TWO    Why sellers care: a letter built on
       checked numbers makes your offer
       [your words for your market].
THREE  What to bring for a real pre-approval:
       [your checklist: pay stubs, W-2s,
       bank statements, ID].
ASK    Want my checklist? Message me "FIRST."
       [Name], [company], NMLS ID #[number]
Once a month, make one long YouTube video, 10 to 15 minutes: "Buying your first home in [your state], from savings to closing." In my video on why experts should show their face, I compare a long video to a free session with you. A buyer who watches this one has spent a quarter hour with you before you ever meet.
Then get more posts out of it. In CreateSocial, Find Clips suggests standalone clips from the guide, each its own vertical video with subtitles. The same recording becomes a LinkedIn carousel of your pre-approval checklist and an email to your list, both in your voice.
Give agents videos their buyers need instead of buying them lunch
Agents send buyers to the lender they trust to keep a deal calm. So give them short videos they can forward to a nervous buyer at 9 p.m. An agent remembers that longer than a sandwich.
Lots of loan officers are done with the lunch route. "I hate chasing the realtors. I find it so demeaning having to pay for someone's lunch to beg them to do business with me," one wrote in an r/loanoriginators thread on getting clients. Lunch asks an agent for a favor. A video that calms their buyer does the agent one.
Five videos worth forwarding, each one a question buyers bring to their agent:
- "Pre-qualified or pre-approved? What your letter tells a seller."
- "Why your payment estimate changed since last week," which is your Thursday video with a buyer's price.
- "From offer accepted to closing, week by week."
- "The money moves I ask buyers to skip until closing day."
- "Help from family for a down payment: what to have ready."
Send one a week to a handful of agents, one at a time. The note ends on a question, because outreach should open a conversation:
Subject: A 60-second video for your buyers

Hi [name],

Buyers keep asking me what "pre-approved"
actually means for their offer. I made a
60-second video that answers it in plain
English: [link]

It's general, with no pitch, so it's fine
to forward to anyone shopping right now.

Quick question: what do your buyers ask you
about financing that you'd rather hand off?
I'll make the next video about that.

[Your name], [company], NMLS ID #[number]
Their answer is next month's video. If three agents say buyers panic about closing costs, film that. The agent's side of this partnership is in social media for realtors, and how to post a video on LinkedIn covers the versions you make for agents.
Film the refinance video while rates are high, before they fall
Record the refinance video now, so past clients know who to call the week rates drop. In FHFA's National Mortgage Database, 22.5% of outstanding mortgages carried a rate of 6% or more at the end of June 2026. That's more than one in five mortgages, each a possible refinance if rates fall far enough.
This fall added more. Freddie Mac's 30-year average hit 7.40% on October 8 and again on October 15, its high for the year. Anyone who locked around then is a refinance candidate if rates keep sliding, and they'll call the loan officer who explained the math first.
LOCKED THIS FALL? WATCH THIS NUMBER (about 75 seconds)
Screen recording over a break-even table,
your camera in a corner.

HOOK   Bought a home this fall, when rates
       were near the year's high? Here's the
       number I'd watch before refinancing.
ONE    What a refinance costs: [closing costs
       in your market, as a range].
TWO    Your break-even: the costs divided by
       the monthly savings. Made-up example:
       $6,000 divided by $200 a month is
       30 months.
THREE  When it's worth it: you'll stay longer
       than the break-even. [Your own rule
       of thumb.]
ASK    Want me to watch your numbers?
       Message me "WATCH."
       [Your approved disclosure line]
       [Name], [company], NMLS ID #[number]
Then text past clients who closed this fall, one at a time:
Hi [name], quick one from [your name].

Rates moved a lot this fall. I'm keeping a
short watch list of past clients who could
save by refinancing if they drop.

Want me to run your numbers and text you if
the break-even ever looks good? Reply WATCH.
Answer RATE, FIRST and WATCH with the next step, not a form
Every series ends with one word to send you, and your reply is where a viewer becomes a file. Have each answer ready before the video goes out:
| They send | You send back | The next step |
|---|---|---|
| RATE | This week's payment math on their price range | A 15-minute call to start a pre-approval |
| FIRST | Your pre-approval checklist | A call once they've gathered it |
| WATCH | Three questions: their rate, their balance and how long they'll stay | A spot on your watch list, and a text when the break-even works |
| An agent: "My buyer asked about this" | The video, and an offer to call the buyer that day | A pre-approval, and an agent who saw how you treat their clients |
Skip the intake form. A buyer who has watched a few of your Thursdays doesn't need a questionnaire, and a form only gives them time to call their cousin's lender. Cut it and get them on a call, as I tell experts in my video on getting clients.
Your profile does the rest: your name, your NMLS ID, one line on who you help ("first-time buyers in [your state]") and one link to book 15 minutes. Then be patient. Buyers watch for a while before they move, so give the plan three to six months, the window I give every expert in my video on speaking gigs.
Keep it to one hour on Thursday and one recording session a month
The whole system takes an hour a week and one afternoon a month. Anything heavier won't survive a busy closing month. Filming something new every day on top of a pipeline is the trap. "That's not content, that's a second job," as I put it in my video on content formats.
| Thursday, from the noon ET release | Job |
|---|---|
| First 10 minutes | Read Freddie Mac's survey. Copy this week's 30-year average, last week's and the date. |
| Next 10 minutes | Do the payment math on your example loan, update the disclosure line and write your one-sentence read. |
| Next 15 minutes | Record it in sections, one block at a time. |
| Next 15 minutes | Cut the stumbles, take out the pauses, add subtitles. |
| Last 10 minutes | Schedule it everywhere and send it to five agents. |
The other three series come from one session a month. Plan it on a different day, because thinking day and recording day are separate jobs. Then record six videos back to back: two first-time myths, two for agents to forward, the refinance watch and the long YouTube guide.
Keep the edit light. In CreateSocial, delete a word from the transcript and it's cut from the video. Remove Silences takes out the pauses, and subtitles go on in one of 11 styles. Then schedule it, and we post it for you once your accounts are connected.
Your next four survey days, planned for a hypothetical independent broker
This broker lends to first-time buyers in one state and wants more agents sending deals. The month starts with the next survey. Thanksgiving falls on Thursday, November 26, so that week's survey comes out on Wednesday.
| Survey day | Rate video (every platform) | Series video | Written post | Send it to |
|---|---|---|---|---|
| Thu, Nov 12 | The week's move on a $400,000 house | Myth: "Most first-time buyers didn't put 20% down" | LinkedIn post: the week's move in three lines | Five agents, with the forward note |
| Thu, Nov 19 | Same template, new numbers | For agents: "Pre-qualified or pre-approved?" | LinkedIn carousel: the pre-approval checklist, one item per slide | Five more agents |
| Wed, Nov 25 | Same template, out a day early | Refinance watch: "Locked this fall? Watch this number" | Email to past clients: join the refinance watch list | A text to each past client who closed since September |
| Thu, Dec 3 | Same template, new numbers | Myth: "One in four first-time buyers got help from family or friends" | The long YouTube guide goes up, with a LinkedIn post pointing to it | Every agent who replied to a note |
From week two, the rate video is a ten-minute fill-in. At month's end, add up the RATE, FIRST and WATCH messages, the agent replies and the pre-approval calls by series. Give next month's session more of the series that led to calls. When one needs a fresh first line, these 60 video hook examples help.
Advisors and insurance agents run the same play on other money moments: see marketing for financial advisors and marketing for insurance agents.
CreateSocial keeps all four series going while you close loans
CreateSocial helps you build a personal brand that brings in borrowers, agent partners and referrals, without content eating the evenings you spend on files. It learns what you know and runs the whole content week, video and written: ideas, scripts, posts, recording, editing, thumbnails and scheduling. Here's the plan above, inside it.
- Ideas for every series. Scan your website and pick the pages, then add your buyer guides, past videos and call notes to your knowledge base. You get 80 personalized ideas a month with hooks, talking points or full scripts. Trending Now shows what your niche is talking about every Monday, and "Ask me first" gets a real buyer moment out of you before it writes.
- Thursday's hour stays an hour. The rate template sits on the teleprompter near your lens, scrolled by hand or at a set pace, and every block is its own section with one-tap retakes. Record at your desk or in the iPhone app.
- The math goes on screen. For the refinance watch, screen recording puts your camera in a bubble over a break-even table with made-up numbers, and a floating window holds your talking points in view.
- The edit is mostly deleting words. Cut words from the transcript and they're cut from the video. Remove Silences clears the pauses, and subtitles in 11 styles reach buyers scrolling with the sound off.
- One video becomes the agent kit. Turn it into a LinkedIn post, an email to past clients, an X thread, a blog post or a LinkedIn carousel with PDF and PNG export, all in your voice. No video that week? Write them straight from your knowledge base.
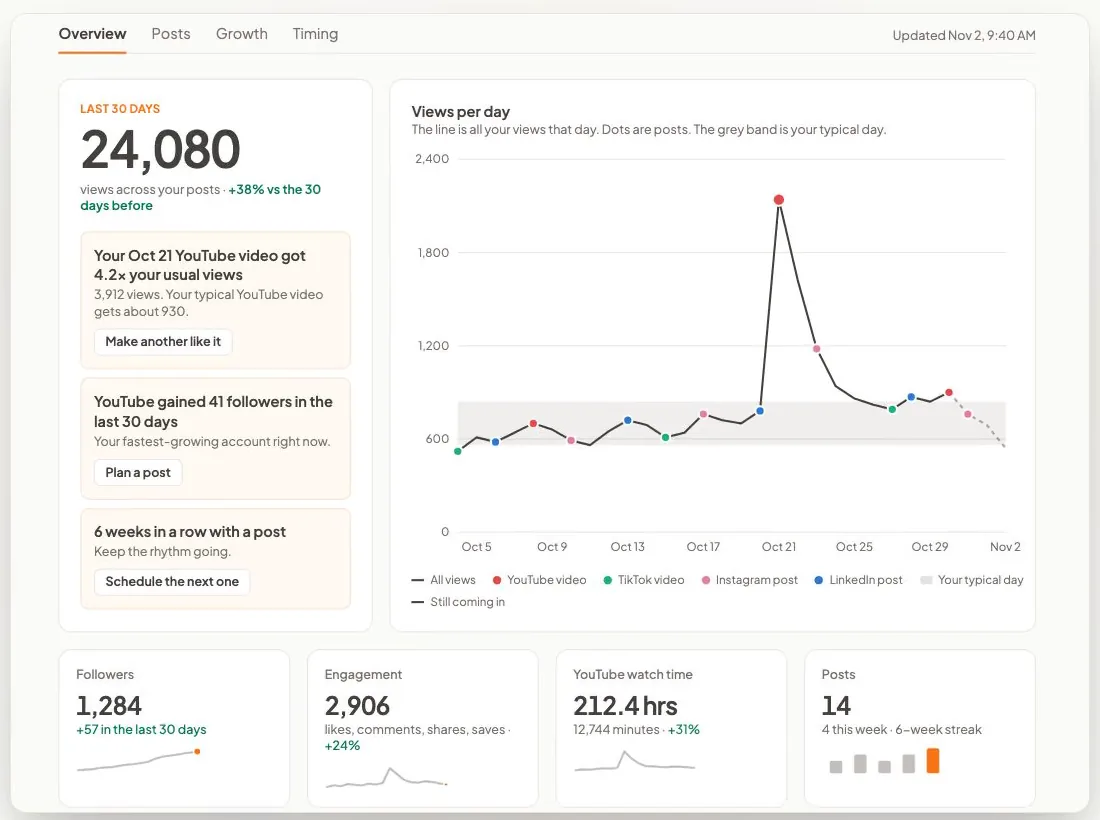
- It goes out while you close loans. Schedule to TikTok, Instagram, YouTube, LinkedIn, Facebook and X with a caption written for each, and we post it for you once your accounts are connected. The Analytics page tracks views, shares and follower growth on your connected TikTok, Instagram, YouTube, LinkedIn and Facebook accounts, and "Make another like it" turns the video that brought calls into next week's idea.
Also in the one plan: competitor tracking for the loan officers whose videos you admire, Dual mode to frame 16:9 and 9:16 in one take, reaction videos in Layout or Stitch mode for the viral mortgage takes your buyers send you, virtual backgrounds with or without a real green screen, eye contact correction, safe-zone guides for TikTok, Reels and Shorts, B-roll from free stock video, and YouTube thumbnails made from your video and photos of you.
I'm Ben Moore, and I built CreateSocial on my own, bootstrapped, here in Cincinnati, Ohio, so you talk to me directly. Feature requests come to me, and a lot of what customers ask for gets built. Before CreateSocial, my agency generated millions of followers and millions of dollars in revenue for its clients, and I've generated hundreds of millions of views. It's the deal you offer agents: a direct line to the person doing the work.
It's $129 a month, or $99 a month billed annually, with no add-ons and no per-feature charges. Start your free trial and have this Thursday's rate video scheduled before Friday. Want to map your four series first? Book a free strategy call with me.
Your first Thursday, from template to three agents
- Copy the rate template, pick your example price and send it to compliance with your disclosure line and NMLS ID.
- At noon ET on Thursday, read Freddie Mac's survey and do the payment math.
- Record it in sections, reading from the teleprompter in a free CreateSocial trial.
- Post it to every platform, then send it to three agents with the forward note.
Then watch for the first reply that starts, "My buyer asked me about this."
Questions people ask
How do mortgage brokers get clients?
Through real estate agents, past clients and the people they send, plus anyone who finds your videos. Nine in ten buyers used a real estate agent or broker in NAR's 2026 Profile, so videos that agents forward and that buyers find when they look you up help every referral land.
How do I market myself as a loan officer?
Pick the buyers you serve best and the agents who work with them. Post one rate video every Thursday and one video a week that answers a first-time buyer or refinance question. Put your NMLS ID and one booking link on every profile, and end each video with a one-word message to send you.
How do you generate leads as a mortgage broker?
Give people an easy reason to message you. A weekly video that turns the rate news into a payment change and ends with "message me RATE" starts conversations, and sending your videos to agents and past clients brings referrals with it. Judge it after three to six months.
What are the best social media platforms for loan officers?
YouTube and Facebook for most buyers. The median first-time buyer was 40 in NAR's 2026 Profile, and in Pew Research Center's 2026 survey 91% of adults aged 30 to 49 used YouTube and 78% used Facebook. Add Instagram and TikTok for younger renters and LinkedIn for agents, then put each video on all of them.
Can loan officers post mortgage rates on social media?
Yes, with care. Under Regulation Z, an ad that states a rate must give the annual percentage rate, and an ad that states a payment, a down payment or a loan term must also give the down payment, the repayment terms and the APR. Put those in one disclosure line, get the format approved by compliance once, and change only the dated numbers each week.
How often should a loan officer post on social media?
One rate video every Thursday plus one or two other videos a week is enough if you keep it up. The rate video takes about an hour after Freddie Mac's noon release, and the rest come from one recording session a month.